Most investors still think of Prologis as the company that owns the warehouse your Amazon package passes through. That framing is becoming obsolete fast.
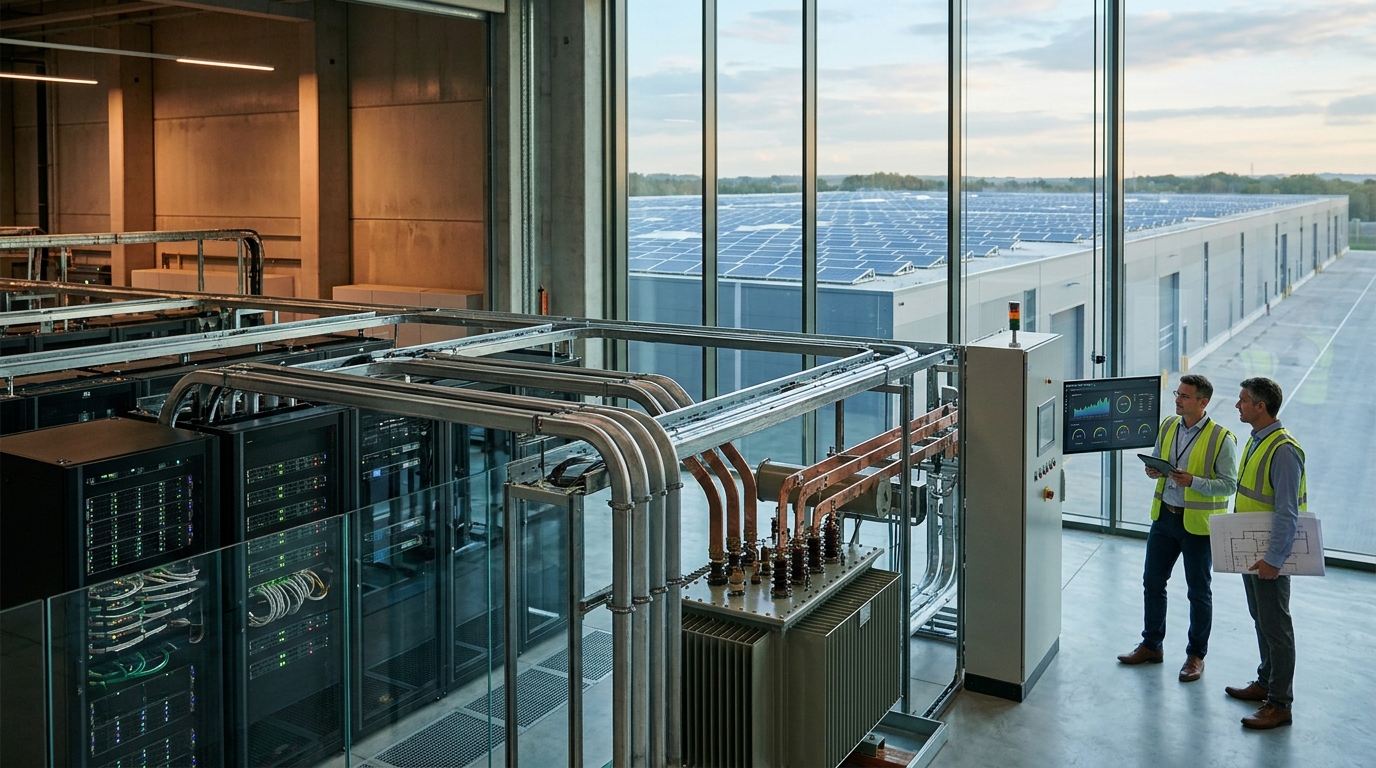
What the numbers actually show is a power utility embedded inside a REIT. As of Q3 2026, Prologis has 5.8 gigawatts in its data center power pipeline, including 1.7 gigawatts of secured power and 4.1 gigawatts in advanced stages, with letters of intent already covering approximately 1 gigawatt. Those are not warehouse metrics. That is infrastructure language, and it belongs alongside Duke Energy or NextEra in a conversation about who controls the grid access that AI computing desperately needs.
Prologis develops primarily in its existing markets, focusing on logistics facilities while also pursuing higher-and-better-use conversions such as data centers. A key enabler of those conversions is its energy procurement strategy: by leveraging scale and relationships with utilities, the company is securing reliable access to power that enhances its land portfolio and enables the conversion of select logistics sites into energy-ready data center developments.
The operational engine is still humming. Prologis achieved core FFO of $1.60 per share in Q3, with occupancy at 95.6% and same-store NOI growth of 5.7%. Rent change on rollover hit 38% on a net effective basis. These are the metrics of a logistics business firing well, and they fund the pivot into digital infrastructure without forcing a choice between the two.
The underappreciated angle is who is driving demand. Data center supply chain customers now account for approximately 10% of new leasing globally and 17% in the United States. That is not rounding-error exposure. It is a structural demand shift pulling directly from the AI buildout, and Prologis captures it on two levels simultaneously: as a logistics landlord serving the companies building data centers, and as a developer building data centers itself.
Management has highlighted more than $2 billion of data center development starts earlier in 2026. The pipeline economics matter here. Prologis has also described its services as addressing the growing convergence of physical, digital and energy infrastructure, and is leveraging its development capabilities, energy solutions and strategic locations to deliver digital infrastructure requirements through selective development of data centers.
Then there is the SEGRO factor, which the market has not fully priced as a data center accelerant. Adding SEGRO would expand Prologis’ European portfolio by 47% to 368 million square feet and give it a development pipeline on the continent totaling 13 million square feet. The transaction would also expand Prologis’ European land bank by 126%. Land near dense population centers is exactly what data center developers cannot manufacture. Prologis is about to own considerably more of it.
The risk worth watching is execution pacing. Analysts have raised concerns that the shift toward capital-intensive data center projects could test funding and balance sheet flexibility. The SEGRO deal is expected to be neutral to slightly dilutive to core FFO in the first full year following closing, scheduled for the first half of 2027. Neither concern kills the thesis. Both deserve weight.
The wealth takeaway is this: the market still prices Prologis as an industrial REIT, which means it applies a warehouse multiple to an asset that increasingly resembles a power and data infrastructure platform. That gap between how the company is classified and what it actually does is where the opportunity sits for investors patient enough to let the data center revenue scale into the valuation.