The French bond market delivered its verdict on October 1, and it was blunt. France’s 10-year OAT yield jumped to about 4.99% intraday before easing, the highest level since 2002. The OAT/Bund spread pushed to post-euro-crisis highs as investors demanded a larger premium to hold French debt.
Equity sentiment reflected the same strain. U.S. index futures were little changed while European index futures edged lower. The CAC 40 finished the week down about 2.24%, weighed by renewed focus on France’s fiscal trajectory.
What the Spread Is Actually Saying
Italy carries debt-to-GDP of roughly 140% and Greece is higher still, yet the market’s message is that France’s political and fiscal execution risk has become the story. France’s debt is expected to approach 122% of GDP, and the calendar matters: the next presidential election is scheduled for April 18 and May 2, 2027. With rates higher, the state’s interest bill is expected to top €90 billion in 2027, with the government putting the figure at €91.2 billion.
France’s own High Council of Public Finances, the independent fiscal watchdog, has warned that the macro assumptions behind the 2027 budget are optimistic. The OECD does not back the “0.4% in 2026” call used here either: its latest Economic Outlook projects France at about 0.7% growth in 2026.
The November 17 Problem
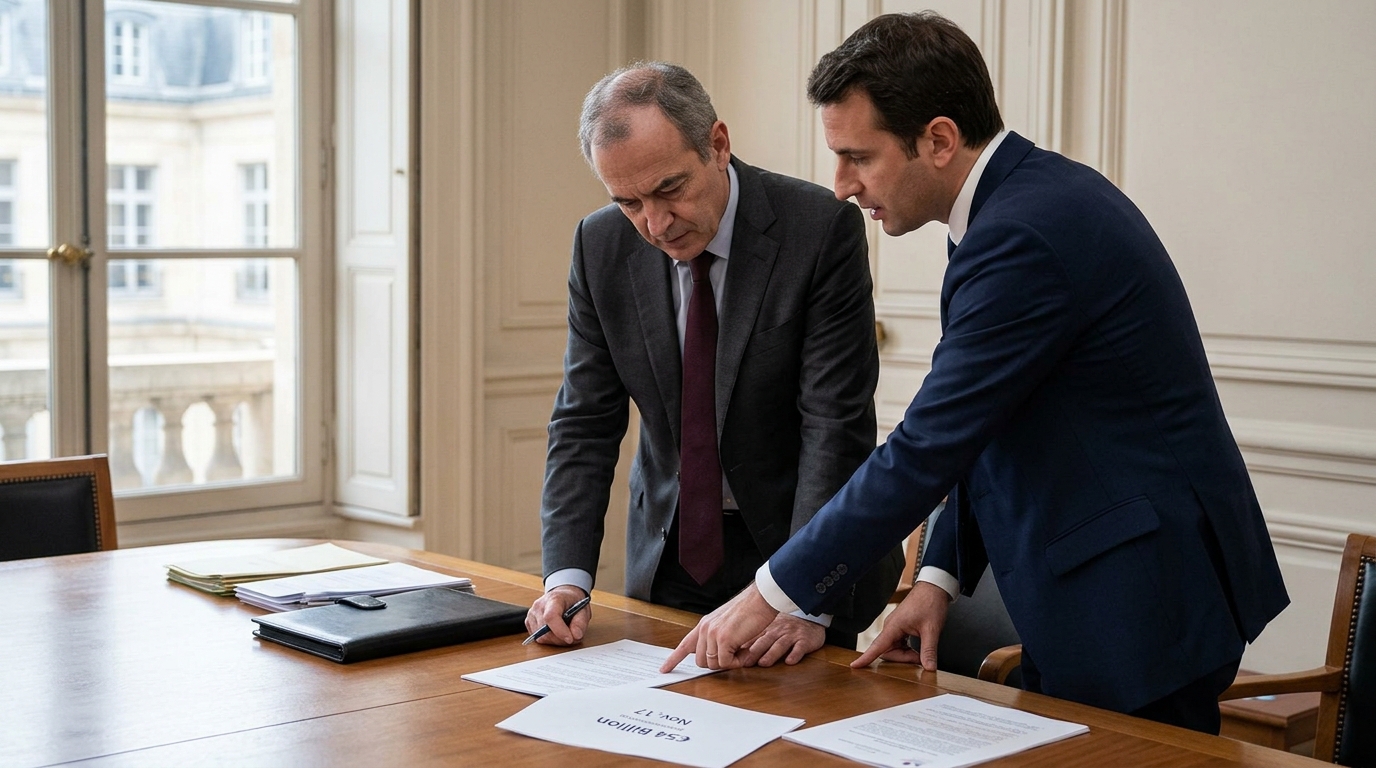
The government has framed the plan as a roughly €54 billion fiscal effort and is targeting a deficit of 5% of GDP in 2027, down from 5.4% in 2026. The parliamentary timetable is tight: the National Assembly has scheduled the final vote on the 2027 budget for Tuesday, November 17.
Getting there is the problem. Ever since France’s July 2024 snap election failed to deliver an absolute majority, political division has repeatedly turned budgets into confidence tests. One government was brought down by a no-confidence vote in December 2024. Separately, the 2026 budget was ultimately considered adopted on February 2, 2026 after the government used Article 49.3 and surviving two no-confidence motions. With no parliamentary majority, Lecornu may again be tempted to use Article 49.3 to force a budget through without a vote, a move that can trigger no-confidence motions and political backlash. BCA Research’s Jérémie Peloso expects substantial back and forth between the government, the National Assembly and the Senate that could run deep into the first half of 2027.
French Banks and the Contagion Question
Stress is showing up most clearly where you would expect: sovereign risk and the banking complex that intermediates it. Credit default swaps tied to major French banks have widened, and French bank equities have been among the most sensitive to each new leg wider in the sovereign spread.
At the same time, some strategists have argued spillover into investment-grade corporate credit remains relatively contained. That is a silver lining, but it also means the stress is concentrated precisely where it is most visible: sovereign debt and the banks that hold it.
The Trading Framework
The November 17 vote is the event risk that structures the next six weeks. If the €54 billion package passes substantially intact and the OAT/Bund spread compresses meaningfully over the following two months, the stress framing is premature and France is executing a painful but functional adjustment. If the budget fails or arrives heavily diluted, the spread has room to widen further, and French bank equities would be repriced alongside it.
Traders with European exposure should treat the OAT yield, not the VIX, as their primary risk gauge through mid-November. The euro’s weakness against the dollar reinforces the same message. Until Lecornu has the votes or the constitutional workaround in hand, France is the variable that caps any sustained risk-on move in European assets.