Friday’s 7.35% single-session gain in SPCX did not happen because Starship flew. It happened because Starship worked. There is a meaningful difference, and that difference is what makes this the most compelling equity situation in the market right now.
Why This Stock Now
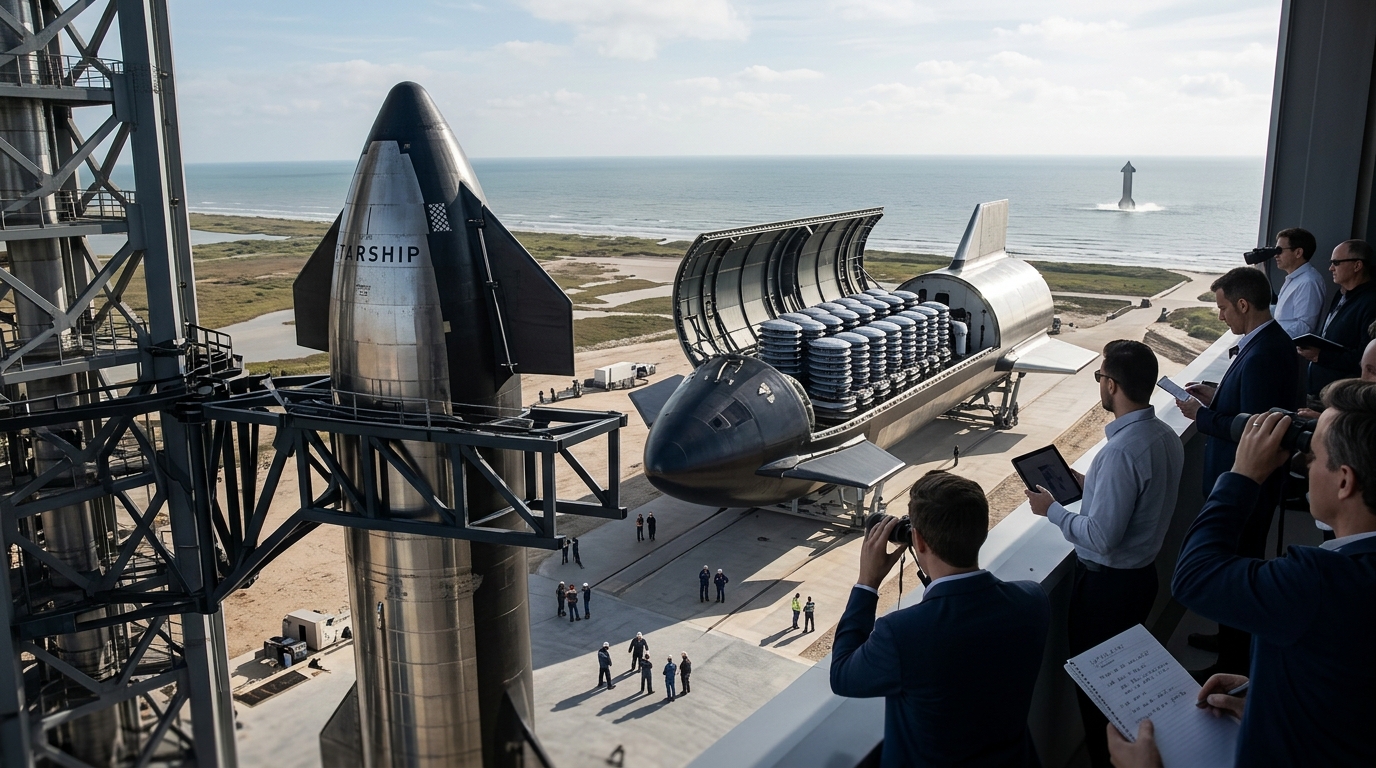
On Monday, September 28, SpaceX’s Starship lifted off from Starbase, Texas, on its 14th flight and delivered 26 Starlink V3 satellites to orbit, the first time Starship has delivered a meaningful payload to orbit. SPCX closed October 2 at $158.96, up 7.35%, on volume of 119,446,900 shares. The follow-through analyst commentary ran all weekend. The stock enters Sunday sitting 18% below its 52-week high of $225.64, with a Wall Street consensus that says it should be considerably higher.
The Business
SpaceX is two companies operating inside one balance sheet. The launch business generates revenue and absorbs the capital that funds Starship development. Starlink is where the cash compounding actually lives.
In the second quarter of 2026, SpaceX reported $7.8 billion in total revenue, an approximately 92% year-over-year increase, posting an earnings-per-share loss of 9 cents against consensus estimates of a 26-cent loss. The trajectory matters more than the current loss: analysts forecast sharply higher revenue growth for the full year.
Why Wall Street Is Paying Attention
Flight 14 closed a debate that had circled the stock since its June 2026 IPO. Starship inserted into orbit at roughly 170 miles up and deployed 26 Starlink V3 satellites, the most advanced Starlink satellites yet. Update: it is widely reported that V3 satellites are larger than prior generations and that Starship can carry far more of them than Falcon 9, but SpaceX has not established publicly that there is no alternative delivery mechanism.
Multiple firms reiterated their positive outlook after the flight. BofA Securities maintained a Buy rating with a $235 price target, while Clear Street reiterated a Buy rating and set a $217 target. Morgan Stanley analyst Adam Jonas held an Overweight rating with a $300 price target and has outlined a $600 bull case. Wall Street’s consensus on SPCX sits at a Moderate Buy with a $235.10 average price target, roughly 48% above Friday’s close.
What’s Driving the Opportunity
Musk has indicated an aggressive deployment goal for Starlink V3 satellites over the next couple of years. The details, timing, and the revenue impact are still subject to execution and regulatory constraints. Every V3 deployed by Starship instead of a smaller launch vehicle further compresses the per-bit cost. SpaceX has also started drawing attention to orbital AI computing under the name Starmind, an emerging effort the market has not yet priced with confidence.
SPCX outperformed major indices last Friday, with the Nasdaq 100 ETF up just over 1% and the S&P 500 ETF rising less than 1% on the same day. Relative strength of that magnitude, at this volume, with this catalyst, is institutional accumulation presenting itself in real time.
What Could Go Wrong
The flight was shortened from a planned nearly ten hours to roughly three. Out of an abundance of caution given an engine issue experienced during ascent, the flight control team decided to limit the duration spent on orbit. Full reusability and rapid cadence, the assumptions that underpin the cost projections, have not been demonstrated.
The supply calendar is the more immediate risk. A 7% tranche of the 180-day lockup block, approximately 328.4 million shares, becomes eligible to trade on October 9, 2026, five days from today (October 4, 2026). Another equivalent tranche follows October 24, 2026. Late October or early November could bring the single largest single-event release, because the IPO lockup terms include an earnings-linked release tied to SpaceX’s third-quarter 2026 results, and the exact date depends on when the company reports. Each tranche creates a supply event the stock must absorb. Valuation compounds the concern: SPCX’s current Price-to-Sales ratio is extraordinarily high compared to typical industry levels, meaning the forgiveness for execution misses is thin.
The Bottom Line
Starship Flight 14 converted a promise into a data point. Twenty-six V3 satellites are now raising their orbits and entering service, and the economics of Starlink just stepped materially forward. The analyst consensus at $235 reflects a credible path. The October lockup tranches and an engine-shortened first flight are the real price of admission, both are risks you must price honestly before you size a position. The opportunity is real. So is the volatility that comes with owning the most closely watched newly public stock on the planet.