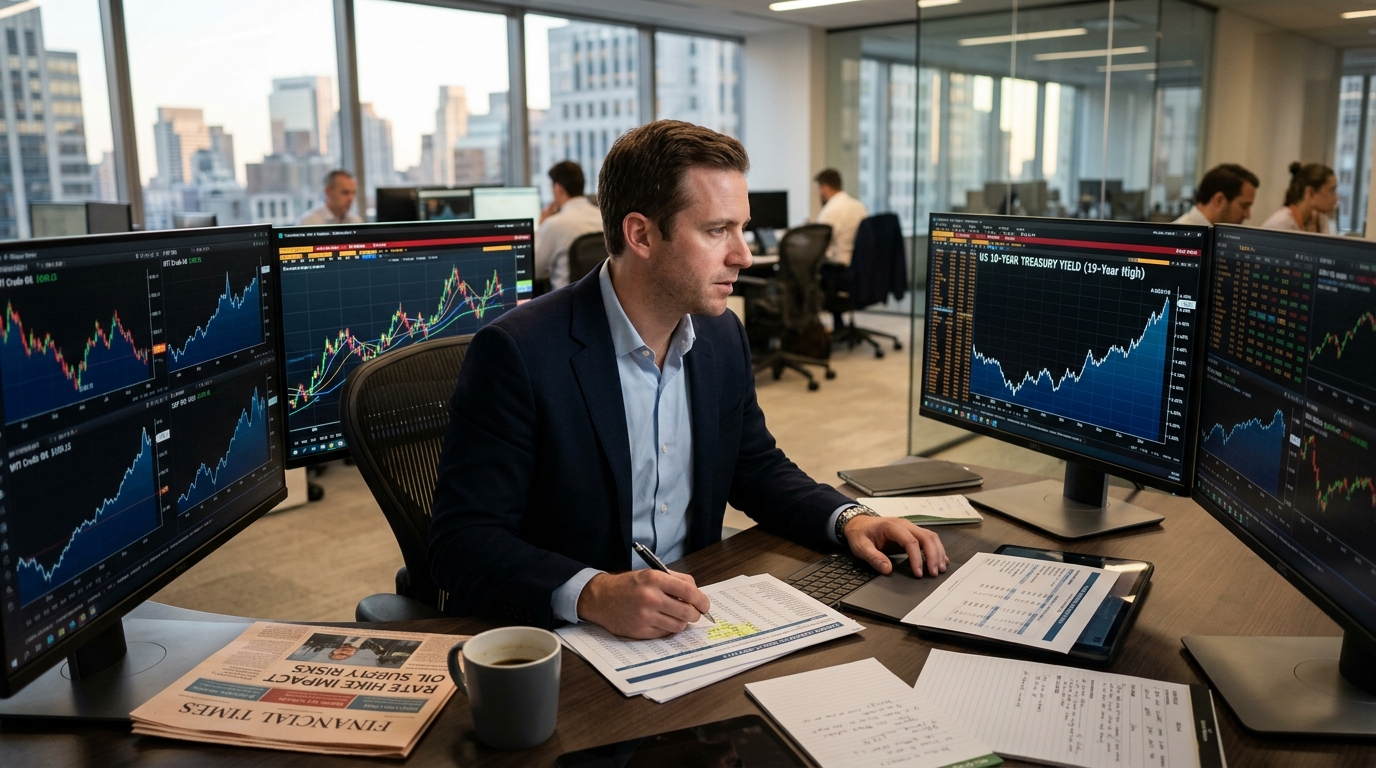
Last week handed investors a lot to process: the Fed’s first rate hike since 2023, a 10-year Treasury yield that briefly touched levels not seen since 2007, and oil above $109 on renewed Middle East supply fears. Now comes the harder part. The week of September 21 will start testing how markets absorb all of it.
1. Where the 10-Year Treasury Goes From Here
This is the number that matters most right now for almost every asset class. The 10-year yield hit 5.041% on September 15, its highest level since July 2007, before pulling back to around 5.00% by Friday as the immediate energy shock cooled and investors digested the Fed decision. Chair Kevin Warsh made clear at his post-meeting press conference that the Fed sees higher long-term yields as partly driven by economic strength, geopolitics, and competition for global capital, not panic. But a sustained hold above 5% would tighten financial conditions for consumers, homeowners, and corporate borrowers without the Fed lifting a finger. Watch how bond markets trade early Monday before any hard data arrives.
2. The September Flash PMIs on Wednesday
The S&P Global flash Manufacturing and Services PMIs drop Wednesday morning at 9:45 a.m. ET, and the timing could not be more pointed. The August composite reading hit a 53-month high at 56.0, powered by a surge in services activity. If September’s preliminary readings show a meaningful deceleration in either services employment or new orders, markets will read it as the Fed hike already biting. A continued acceleration, especially with renewed price pressure, keeps the October meeting very much live for another 25 basis points.
3. AutoZone and the Consumer Spending Signal
AutoZone reports Q4 fiscal 2026 earnings before the open on Tuesday. The company has confirmed the release date, but the specific consensus revenue and EPS figures can shift right up to the report. AutoZone is one of the cleaner read-throughs on how consumers are managing an aging vehicle fleet under pressure from high fuel costs and elevated borrowing rates. When households can’t afford new cars, they repair old ones. If commercial sales, the segment covering professional repair shops, accelerate sharply, that confirms stress is spreading beyond individual consumers.
4. Costco’s Earnings and the Special Dividend Question
Costco closes out the week Thursday afternoon, with Wall Street bracing for another strong quarter. The stock has beaten EPS estimates in each of the last five quarters. But the number that generates the most buzz this cycle isn’t the headline figure. Costco declared a $15-per-share special dividend in December 2023, and history suggests another one-time distribution could show up again when cash builds enough to make it attractive. Management commentary on cash levels during the September 24 call could signal whether that payout is inching closer. The membership renewal rate and e-commerce comparable sales, up 17.9% in August, are also worth tracking closely as margin pressure from higher costs persists.
5. Oil and the Strait of Hormuz Talks
Brent crude surged above $109 in early September after renewed attacks on shipping and energy infrastructure, following a temporary pullback to the mid-$80s earlier this summer. President Trump is expected to meet with Gulf leaders next week, and any concrete movement toward restoring more normal traffic through the Strait of Hormuz would be among the biggest disinflationary catalysts available right now. Markets will trade the geopolitical headlines in real time. Every dollar Brent drops keeps a rate hike in October slightly less certain. Every dollar it gains does the opposite.
The week doesn’t have a single dominant earnings story. It has five pressure points, each measuring a different dimension of the same stress: inflation that is too sticky to ignore, rates that are rising at a pace the economy hasn’t seen in years, and consumers making quiet, revealing choices about how to spend what’s left. Pay attention to the sequence. Wednesday’s PMI data lands before Costco speaks Thursday, which means markets will arrive at that earnings call already primed by the broadest read on business conditions available.